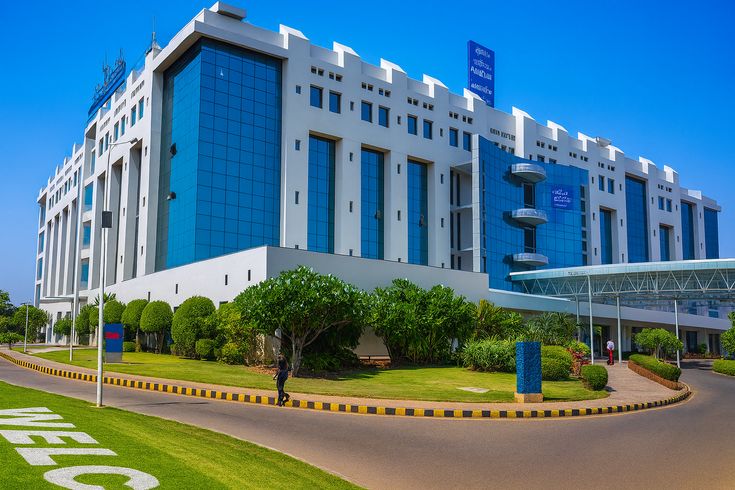
India’s premier integrated healthcare provider with 73 hospitals (10,134 beds), large retail pharmacy chain, diagnostics, and telemedicine services. Strong growth pipeline with ₹7,600 Cr expansion (4,300 beds) and leadership in digital health.
Apollo Hospitals Enterprise Limited is India's premier integrated healthcare services provider, operating in the healthcare sector with a focus on multispecialty hospital operations, pharmacy retail, diagnostics, and telemedicine services.
Established in 1983 by Dr. Prathap C Reddy, Apollo Hospitals pioneered the private healthcare revolution in India as the nation's first corporate hospital. The company has emerged as Asia's foremost integrated healthcare services provider with a robust presence across the healthcare ecosystem.
Recent Developments:
| Market Capitalization | ₹98,931 Crores |
| Current Stock Price | ₹6,880 |
| 52-Week High/Low | ₹7,545 / ₹5,691 |
| Price-to-Earnings Ratio | 68.4x |
| Price-to-Book Ratio | 12.0x |
| Metric | FY25 | FY24 | FY23 | FY22 | FY21 |
|---|---|---|---|---|---|
| Return on Equity (%) | 19.1 | 15.0 | 14.0 | 17.0 | 8.0 |
| Return on Capital Employed (%) | 17.1 | 15.0 | 14.0 | 17.0 | 8.0 |
| Net Profit Margin (%) | 6.9 | 4.9 | 5.1 | 7.6 | 1.3 |
| Operating Profit Margin (%) | 13.9 | 12.6 | 12.4 | 14.9 | 10.8 |
| Revenue Growth (5-year CAGR) | 14% |
| Profit Growth (5-year CAGR) | 37% |
| EPS Growth (5-year CAGR) | 36.7% |
| Stock Price CAGR (5 years) | 38% |
| Debt-to-Equity Ratio | 0.3 |
| Book Value per Share | ₹571 |
| Working Capital Days | 36 days (FY25) |
| Cash Conversion Cycle | -6 days (FY25) |
| Operating Cash Flow (FY25) | ₹1,920 Cr |
| Free Cash Flow Trend | Improving |
| Capex (FY25) | ₹1,537 Cr |
| Dividend Yield | 0.23% |
| Dividend Payout Ratio | 26.6% |
| Dividend Per Share (FY25) | ₹19 |
| Category | Shareholding % | Trend |
|---|---|---|
| Promoter Holding | 29.3% | Stable |
| Foreign Institutional Investors | ~25-30% | Increasing |
| Domestic Institutional Investors | ~15-20% | Stable to Increasing |
| Public Shareholding | ~70.7% | Strong liquidity |
Apollo is well-positioned to capitalize on India's healthcare transformation with its integrated platform approach, strong brand recognition, and operational excellence. The company's focus on digital innovation and quality healthcare delivery provides sustainable competitive advantages.
| P/E Based Valuation | ₹7,200 - ₹7,800 |
| EV/EBITDA Multiple | ₹7,000 - ₹7,600 |
| DCF Analysis | ₹7,400 - ₹7,900 |
| Asset-based Valuation | ₹6,800 - ₹7,400 |
Target Price: ₹7,500 (9% upside)
Expected to achieve target price as expansion projects commence and digital initiatives scale up.
Apollo Hospitals Enterprise Limited represents a compelling investment opportunity in India's rapidly growing healthcare sector. The company's strong market position, consistent financial performance, and clear growth strategy make it an attractive long-term investment.
While the stock trades at premium valuations, the growth prospects, market opportunity, and execution track record justify the investment. The ongoing capacity expansion and digital transformation initiatives position Apollo well for sustained growth in the coming years.
Target Price: ₹7,500 | Investment Horizon: 12-18 months